For most taxpayers, the process runs about six months to a year from the day the IRS accepts your offer for processing to the day you get a decision. Complex cases, including those with business income, multiple properties, or disputed asset values, can take longer. Federal law caps the wait at 24 months. If the IRS has not rejected your offer by then, it is automatically accepted. Here is what happens at each stage, what slows an offer in compromise down, and what you can do while you wait.
Quick answer for “how long does offer in compromise take?”: Most straightforward offers get a decision in six to twelve months. The IRS says a complete investigation can run up to 24 months for complicated cases, and the law backs that number up: an offer that is not rejected within 24 months is automatically treated as accepted.
Offer in Compromise Timeline at a Glance
Here is how long an offer in compromise takes, broken down stage by stage:
- Submission and initial screening: 2 to 4 weeks
- Assignment to an offer examiner: 1 to 3 months, depending on office caseload
- Financial investigation: 3 months to a year or more, depending on complexity
- Written decision once the investigation closes: a few weeks after the examiner’s review wraps up
- Legal maximum before an offer is deemed accepted by default: 24 months from submission
These ranges assume a complete, accurate application. Each one can stretch if the IRS has to come back to you for missing information, which is the most common reason an offer in compromise timeline runs longer than expected.
What Happens During an Offer in Compromise: Step by Step
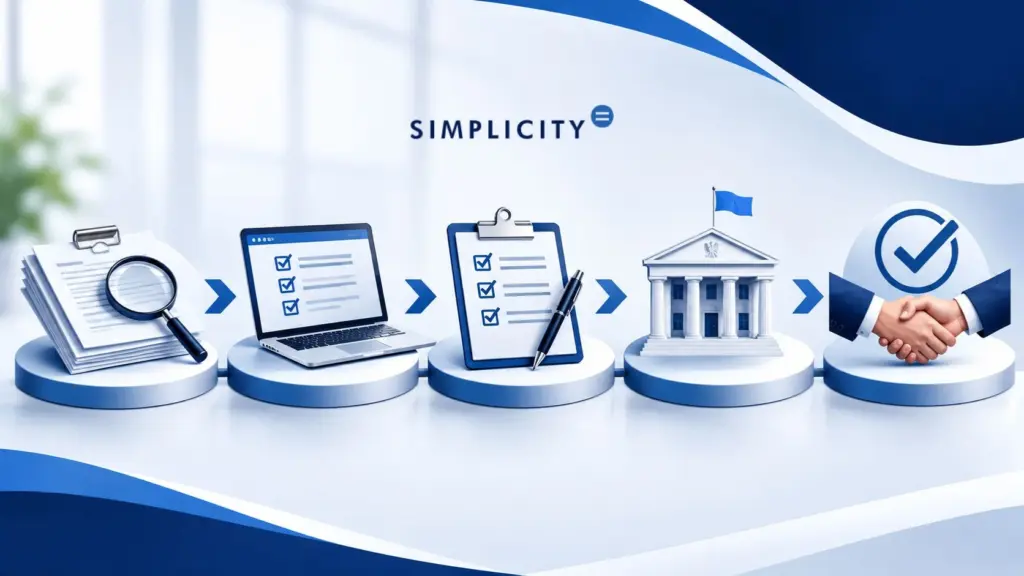
An Offer in Compromise, or OIC, lets you settle a tax debt for less than the full amount you owe when the IRS agrees you cannot pay it in full. Getting from submitting an offer to a final decision generally follows four stages, and understanding them is the easiest way to understand offer in compromise processing time.
1. Submission and Initial Screening
After you mail Form 656, your financial statements, the $205 application fee, and your initial payment, the IRS first checks that your paperwork is complete and that you meet the basic filing requirements. You must be current on filing all required returns and any estimated tax payments for the current year, and you cannot be in an open bankruptcy case. According to the Taxpayer Advocate Service, your offer must clear this screening step before the IRS will start evaluating it.
If something is missing, your entire package, including the application fee, comes back to you. This is called a return, and it is different from a rejection. The 24-month clock does not start until you resubmit a complete offer, which is why a careful first submission matters more than almost anything else in the whole process.
2. Assignment to an Offer Examiner
Once your offer is accepted for processing, it sits in a queue until it is assigned to an offer examiner in a Centralized Offer in Compromise unit or, for more complicated cases, an offer specialist in a local field office. How long this step takes depends on how many open cases that office is already carrying. This is one reason offer in compromise processing time can vary so much from one taxpayer to the next, even when the underlying tax debt looks similar on paper.
3. The Financial Investigation
This is where most of the time goes. Using Form 433-A (OIC) or Form 433-B (OIC), the examiner verifies your income, expenses, assets, and tax compliance against the IRS’s own national and local expense standards, then calculates your Reasonable Collection Potential, the amount the IRS believes it could realistically collect from you through your assets and future income.
The examiner may contact you by phone or mail for additional documentation, such as bank statements, pay stubs, or proof of a specific expense. A slow or incomplete response can pause your case or get it returned without appeal rights, so staying organized and responsive matters most at this stage.
4. The Decision
Once the investigation closes, you receive a written decision. An acceptance letter spells out your payment terms and the five-year compliance period that follows. A rejection letter explains the reason, and you generally have 30 days to appeal a rejected offer. A return is different from a rejection: it usually means something in your file, such as a new balance due or an open bankruptcy, made the offer unprocessable, and appeal rights are limited in that case. According to the IRS, the complete offer investigation can take up to 24 months, depending on inventory levels and case complexity.
The 24-Month Rule: When an Offer Is Deemed Accepted
Here is something most taxpayers do not know. The IRS does not get unlimited time to decide. Under Internal Revenue Code Section 7122(f), an offer is automatically treated as accepted if the IRS has not rejected it within 24 months of the date you submitted it.
A few details matter here. The clock only runs while your offer is actively pending, so time spent disputing the underlying tax debt in court does not count against the 24 months. And if the IRS returns your offer, rather than rejecting it, within that window, even close to the deadline, the deemed accepted rule does not apply, since a return is not a rejection. Tax Court cases on this exact issue have turned on that distinction.
In practice, very few offers actually reach deemed acceptance, because the IRS tracks its own inventory against that 24-month deadline. Treat the rule as a backstop against indefinite delay, not something to plan your finances around. If anyone tells you an offer in compromise is guaranteed to resolve on a specific date because of this rule, that is not how it works in practice.
A Realistic Example: Simple Case vs. Complex Case
Two taxpayers filing in the same month can have very different timelines. Consider a single W-2 employee with one bank account, no real estate, and a straightforward tax debt from a single bad year. A complete, well-documented offer like that can realistically get a decision in six to nine months once it reaches an examiner.
Now consider a small business owner with a side rental property, a retirement account, and tax debt spanning three years across both personal and business returns. The examiner must verify two sets of books, apply both personal and business expense standards, and resolve any inconsistencies between them. That same offer, submitted the same month, might easily take 15 to 20 months before you see a final decision. Neither taxpayer did anything wrong. The complexity of what the IRS must verify drives offer in compromise duration more than almost anything else.
A church or nonprofit staff member’s offer can fall somewhere in between. Clergy housing allowance, dual employment status for SECA purposes, and any parsonage-related income all need to be sorted out correctly before the IRS can calculate an accurate Reasonable Collection Potential. An offer that misstates how housing allowance interacts with self-employment tax is a common reason these cases get sent back for more information, which can add months to an otherwise straightforward case.
What Can Make an Offer in Compromise Take Longer
Some factors are within your control, and some are not. The most common sources of delay include:
- Incomplete paperwork: a missing signature, an unsigned financial statement, or a documentation gap is the single biggest cause of returned offers and restarted timelines.
- Business ownership: if you run a business, the IRS has to evaluate both your personal and business finances, which roughly doubles the documentation involved.
- Multiple income sources or properties: rental income, retirement accounts, and real estate each require separate verification.
- An open audit or pending innocent spouse claim: the IRS generally will not investigate your offer until that matter is resolved first.
- Falling out of compliance: missing a current-year estimated payment or filing deadline while your offer is pending can stall or return your case.
- Appeals after a rejection: appealing a rejected offer adds its own review period on top of the original investigation, which can extend the total timeline by several more months.
- A high inventory at the assigned office: offer examiners work through cases in the order received, so staffing and caseload affect how long your offer in compromise sits in the queue before anyone even looks at it.
Does the Type of Offer Affect the Timeline?
The IRS allows two payment structures, and the choice affects your cash flow more than your processing time, but it is worth understanding:
- A lump sum offer requires 20 percent of the offer amount up front, with the balance paid in five or fewer payments after acceptance.
- A periodic payment offer spreads the full amount over up to 24 months and requires you to keep making those monthly payments while the IRS investigates your case.
If you stop making periodic payments during the investigation, the IRS can withdraw your offer entirely, which effectively restarts your timeline from zero with a new submission. For that reason, extended offer processing time almost always results from a lapse in required payments or documentation, not the payment structure itself.
Either structure uses the same $205 application fee and the same investigation process once your offer reaches an examiner. Choosing lump sum over periodic payments does not move you to the front of the queue. Whether you are asking how long an IRS offer in compromise takes for a lump sum or a periodic offer, the answer comes down to the investigation stage described above, not the payment structure itself.
Can You Speed Up an Offer in Compromise? Fast Track Mediation
There is no formal way to expedite the overall review, but there is one option worth knowing about if you reach a specific disagreement with the examiner’s numbers. The IRS offers Fast Track Mediation, a voluntary program that brings in an Appeals mediator to help resolve a single disputed issue, such as your allowable living expenses, without waiting for a full rejection and appeal.
Fast Track Mediation only applies while your offer is still under investigation. Once you receive a rejection letter, this option is no longer available, and your only path forward is the standard appeal within 30 days.
A Licensed CPA’s Perspective on Offer in Compromise Timing
Most of what you read about Offer in Compromise timelines comes from companies that process paperwork without ever working a case through to decision. This guide comes from doing that work directly: calculating Reasonable Collection Potential before a client files, catching paperwork gaps that get an offer returned, and knowing which examiner requests are routine versus signs something needs a second look.
Shaun Glenn, CPA, MSA, MST, has spent more than 15 years handling cases like this for pastors, nonprofit staff, schools, and closely held businesses across Southern California, where housing allowance and multi-entity structures often complicate the Reasonable Collection Potential calculation in ways a generalist resolution company would miss. When a church administrator or a small business owner asks how long their own offer will take, the honest answer depends on the specifics of their file, and that’s a judgment call that comes from having handled the process before.
Talk to a CPA Before You File or While You Wait
If you are trying to decide whether an Offer in Compromise makes sense for your situation, or you already filed one and want a CPA in California to check in on it, you can book a phone call or schedule a Zoom call with Shaun to review your numbers and outline your options before your next step.
FAQs About the OIC Timeline
How long does an Offer in Compromise take once the IRS has everything it needs?
Even with a complete file, expect at least several months, since the examiner still has to independently verify every number against IRS standards before calculating your Reasonable Collection Potential.
What is the success rate of an Offer in Compromise?
In the IRS’s most recently published full-year collection statistics, the agency received 33,591 Offers in Compromise and accepted 7,199, an acceptance rate of about 21 percent. Your own odds depend on whether your offer matches your Reasonable Collection Potential, not on that average.
How much will the IRS accept for an Offer in Compromise?
There is no fixed percentage or standard discount. The IRS sets a minimum acceptable offer using its Reasonable Collection Potential formula: your net realizable equity in assets plus what it determines you could pay from future income, so a CPA needs to review your specific numbers to know what’s realistic.
What is the downside of an Offer in Compromise?
An accepted offer requires five years of on-time filing and payment, the IRS keeps your refund for the acceptance year, and the $205 fee is not refunded if you’re rejected or returned. It’s also a long, document-heavy process that not everyone qualifies for.
How do I know if my Offer in Compromise is approved?
The IRS notifies you in writing with a formal acceptance letter, never by phone. If you believe your offer was accepted but you never got the letter, your CPA can request a copy of the case file.
What if my Offer in Compromise is taking longer than the IRS’s own estimate?
A case past six to twelve months usually just means a heavier caseload or outstanding documentation, not a problem. The 24-month deemed-acceptance rule is the only hard legal deadline, and most offers are decided well before that.
Disclaimer: This article is for general informational purposes only and does not constitute tax, legal, or financial advice. Offer in Compromise eligibility, timelines, and outcomes depend on each taxpayer’s individual financial situation, and acceptance is never guaranteed. Reading this article does not create a client relationship with Simplicity Financial. For guidance specific to your situation, consult a licensed CPA.