An offer in compromise (OIC) is an official IRS program that lets eligible taxpayers settle federal tax debt for less than the full amount owed. Understanding what an offer in compromise is, and whether it applies to your situation, is the first step toward resolving serious tax debt. Not everyone qualifies, and the IRS calculates a minimum acceptable offer based on your assets and income. This guide explains how OIC works, who qualifies, how to calculate your offer, and what to expect once you submit your offer.
What Is an Offer in Compromise (OIC)?
An offer in compromise is an IRS program that allows eligible taxpayers to settle their federal tax debt for less than the full amount they owe. Think of it like negotiating with a creditor who decides it’s better to accept 60 cents on the dollar today than chase unpaid debt for years. The IRS takes the same practical view: if it can’t realistically collect the full balance, accepting a reasonable offer makes more sense than endless pursuit.
This is an official IRS program, not a loophole or a late-night infomercial gimmick. An OIC can cover federal income taxes, payroll taxes, and certain penalties. It’s a legitimate resolution path for taxpayers facing genuine financial hardship.
An offer in compromise lets you settle your tax debt for less than the full amount you owe, but only if you meet specific criteria. The IRS weighs whether your offer reflects the most it can realistically expect to collect given your current financial picture. That standard is called your “reasonable collection potential,” or RCP.
The Three Legal Grounds for an IRS Offer in Compromise
The IRS offers tax resolution strategies to settle your account through an offer in compromise. Most competing resources barely explain all three clearly. Here’s a practical decision framework to help you identify your strongest path before you spend a dollar on professional fees.
Doubt as to Collectibility (DATC)
Doubt as to collectibility is the most common ground for an IRS offer in compromise. The IRS doubts it can ever collect the full amount based on your current assets and income. You submit this using Form 656. Ask yourself: “Even if the IRS tried everything, could it realistically collect what I owe?” If the answer is no based on your financial reality, DATC is likely your path.
Doubt as to Liability (DATL)
Doubt as to liability applies when you genuinely dispute the accuracy of the tax debt itself. Think of it like disputing a line item on a bill because the math is simply wrong. This isn’t about being unable to pay; it’s about challenging whether the IRS calculated the debt correctly. DATL uses Form 656-L instead of the standard Form 656. This ground is less common but powerful when there’s a real factual or legal dispute about what you actually owe.
Effective Tax Administration (ETA)
ETA is the rarest of the three grounds, but it can be the most powerful in the right situation. Under ETA, the debt is valid and collectible, but paying it in full would create severe economic hardship or produce an inequitable result. A taxpayer who would lose their primary residence to satisfy the debt is one example of a situation where ETA may apply. The IRS has significant discretion here, so these cases require strong documentation and experienced representation.
Who Qualifies for an Offer in Compromise?
The IRS has a clear eligibility checklist before it reviews a tax debt compromise program application. You must meet all of the following:
- All required federal tax returns have been filed
- All required estimated tax payments for the current year are current
- You are not in an open bankruptcy proceeding
- You have made required federal tax deposits if you’re a business owner with employees
Beyond those baseline requirements, the IRS evaluates four factors to determine your IRS offer in compromise eligibility:
- Ability to pay: what’s left after allowable expenses, weighed against your assets and future earning potential
- Income: both current earnings and expected future income
- Expenses: allowable living costs under IRS Collection Financial Standards, not your actual spending
- Asset equity: the net realizable value of property, bank accounts, retirement accounts, and vehicles
The IRS calculates your reasonable collection potential (RCP) using these four factors. Your offer must generally equal or exceed your RCP, or the IRS will reject it.
Low-income taxpayers may qualify for a fee and payment waiver if household income is at or below 250% of the federal poverty level, as defined in the IRS’s official low-income certification guidelines. Self-employed individuals or those with irregular income may face a different RCP calculation because the IRS may average or project income differently than a straightforward W-2 situation.
One of the most common disqualifiers is unfiled tax returns. You cannot submit an OIC application while missing returns, and any application sent with missing filings will be returned without review. File everything first, then apply.
How Much Should You Offer? Understanding the OIC Calculation
The minimum acceptable offer amount is calculated using a two-part formula, and most competing resources describe it loosely without showing the math. Here’s how it works with real numbers.
Minimum Offer = Net Realizable Asset Equity + Future Income
Net realizable asset equity is the quick-sale value of your assets minus liabilities secured by those assets. For real estate, vehicles, and similar hard assets, the IRS uses approximately 80% of fair market value as the quick-sale value, not full market price. Cash, bank accounts, and similar liquid assets are generally counted at full value, with no markdown.
Future income is your monthly disposable income multiplied by a factor based on how you plan to pay:
- Lump-sum offer: disposable income × 12
- Periodic payment plan: disposable income × 24
Worked example:
- Suppose a taxpayer owes $40,000 to the IRS.
- Home equity at quick-sale value (80% of FMV minus mortgage): $8,000
- Monthly disposable income (income minus IRS-allowable expenses): $300
- Lump-sum multiplier: $300 × 12 = $3,600
- Minimum offer: $8,000 + $3,600 = $11,600
Offering below your RCP almost guarantees rejection. Rounding up slightly above your calculated minimum can make a meaningful difference in whether the IRS accepts or rejects your submission. Running these numbers yourself first, using an Offer in Compromise calculator, gives you a preliminary read before you commit to preparing a full application.
What Documentation Does the IRS Expect to See?
The financial disclosure forms ask for specific supporting records, and organizations that gather these upfront tend to move through the process faster.
- Bank statements for the past several months, for every account tied to the organization or individual.
- Recent pay stubs or income records, including any parsonage or housing allowance for clergy.
- A list of outstanding liabilities, including any other loans or lines of credit.
- Documentation of restricted funds, grant agreements, or donor restrictions (for nonprofits and churches specifically).
- Vehicle titles, property records, or other asset documentation.
This is also where clean, current books make a real difference. An organization with reconciled accounts and organized records can typically pull this documentation together in days. One with months of unreconciled bookkeeping often spends longer assembling the application than the IRS spends reviewing it.
How to Apply for an Offer in Compromise: Step-by-Step
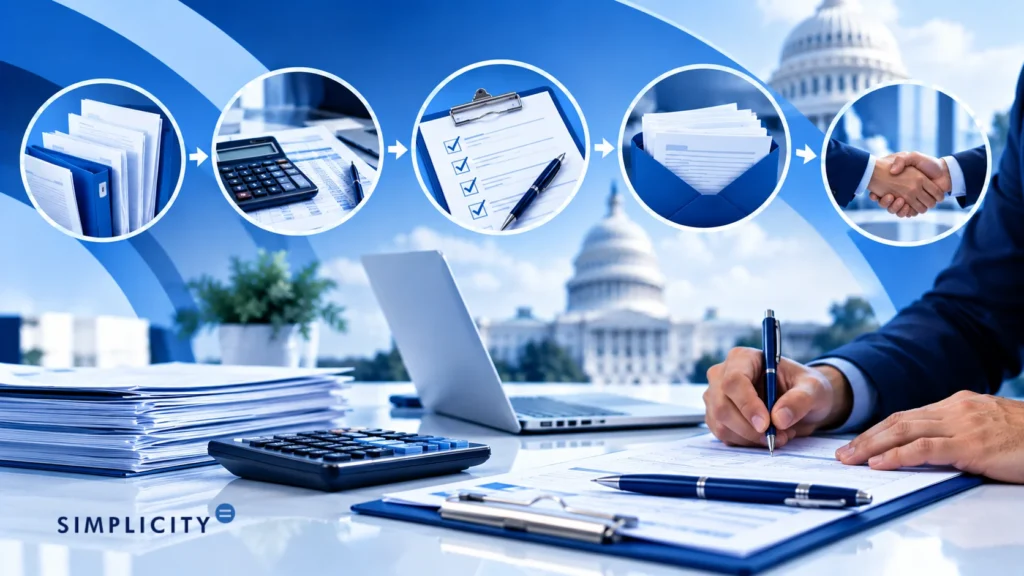
Applying for an offer in compromise follows a specific sequence, and skipping any step will get your application returned without review.
Step 1: Check Eligibility
Run your numbers through the IRS Offer in Compromise Pre-Qualifier Tool before preparing paperwork. It’s a useful first read, though it uses simplified inputs and can miss things a full financial review would catch.
Step 2: File All Overdue Returns
Submit every unfiled return, and keep all required estimated tax payments current, or the IRS will reject your application without reviewing it. For an organization with a few years of unreconciled books, this is often the slowest step to clear.
Step 3: Complete the Required Forms
For a doubt as to collectibility or effective tax administration offer, this means Form 656, the standard OIC application, plus Form 433-A (OIC) for individuals or Form 433-B (OIC) for businesses, documenting income, expenses, and assets in detail. For a doubt as to liability offer, you file Form 656-L instead, on its own, since you’re disputing the amount of the debt itself rather than your ability to pay it.
For Form 433-A/433-B filers, the IRS cross-checks these figures against your bank records and tax filings, so numbers that don’t match, including restricted fund documentation for churches and nonprofits, are a common reason applications stall.
Step 4: Include Your Payment and Fee
Submit the $205 application fee plus your initial payment: 20 percent of the offer for lump-sum applications, or the first installment for periodic payment plans. Taxpayers who meet the IRS low-income certification guidelines can complete Form 656 to waive both.
Step 5: Submit the Application
Eligible individual filers can submit and pay online through their IRS Individual Online Account. Business taxpayers currently mail the complete package, Form 656 and Form 433-B (OIC), to the address listed in the Form 656-B instructions.
Step 6: Keep Paying During Review
Periodic payment applicants must continue the remaining monthly installments while the IRS reviews the offer. Missing an installment (other than the first) can lead the IRS to treat the offer as withdrawn, restarting the process.
During review, the IRS generally suspends other collection activity, but any existing federal tax lien stays in place until you’ve satisfied every term of an accepted offer, not just made the final payment. There’s no fixed processing time; it depends on how complete the application is and the IRS’s current workload. One built-in protection: under 26 U.S. Code Section 7122, if the IRS hasn’t made a determination within two years of receiving your offer, it’s automatically treated as accepted. That’s a legal backstop, not a typical timeline, and most complete, well-documented offers are decided well before that point.
None of these steps require a CPA by law, but the two outcomes that cost the most time, an application rejected for incomplete or inconsistent documentation and an offer withdrawn over a missed payment, are exactly what a CPA reviewing your numbers before you file is positioned to catch. Simplicity Financial’s role is that review, not a promised result before it happens.
What Happens After You Submit Your Offer?
Once your offer in compromise is submitted, a few things happen automatically. Your payments and fees are applied to your tax liability. The IRS may file a notice of federal tax lien. Other collection activity generally pauses while your offer is under review, and the IRS’s collection period is extended to account for the review time.
If the IRS Accepts Your Offer
You will need to meet every term listed in your accepted offer, including filing all required returns on time and making every scheduled payment. The IRS will not release any existing federal tax lien until you have satisfied the full terms of the offer, not just made the final payment.
If the IRS Rejects Your Offer
A rejection is not always the end of the road. You generally have 30 days to appeal using Form 13711, and the IRS Independent Office of Appeals reviews rejected offers separately from the original examiner. Many organizations rejected on a first offer either didn’t fully document their financial picture or applied under the wrong ground for compromise.
Common Reasons Offers Get Rejected
A CPA who reviews these applications regularly sees the same mistakes show up again and again.
- Incomplete or inconsistent financial disclosure. The IRS cross-checks the numbers on your Form 433 against your actual bank records and tax filings. Gaps get noticed.
- Applying under the wrong ground. Submitting a doubt as to collectibility offer when your real issue is a disputed assessment, or the reverse, wastes months of review time.
- Offering an amount below your actual reasonable collection potential. If your calculated RCP is higher than what you offered, rejection is close to automatic.
Working with a firm that promises an outcome before reviewing your full financial picture. If you are evaluating who to work with on a resolution, it is worth understanding what separates a licensed CPA firm from a marketing-driven tax relief company before you sign anything.
How Simplicity Financial Approaches Offer in Compromise Reviews
An offer in compromise touches some of the most consequential numbers in an organization’s finances, which is why the IRS and Google both treat it as high-stakes.
Shaun Glenn, CPA, MSA, MST, is a CPA in California with more than 15 years of experience focused exclusively on nonprofit and church finance:
- Fund accounting: keeping restricted or grant dollars separate from what’s actually available for collection
- Form 990 preparation: shaping how an organization’s assets and income get documented
- Clergy compensation and housing allowance: common in individual offers tied to church staff
That specialization matters because an offer’s reasonable collection potential depends on knowing which assets and income are genuinely available, not just what a standard financial disclosure form assumes.
This is the foundation of Simplicity Financial’s tax resolution services. Every offer in compromise gets reviewed against your actual books, your actual restrictions, and your actual documentation, not against a template.
Talk to a CPA Before You File
If you are behind on a tax balance and trying to figure out whether an offer in compromise, a payment plan, or Currently Not Collectible status fits your situation, the most useful next step is a conversation before a filing. You can schedule a phone call or schedule a Zoom call with Simplicity Financial to review your specific numbers and walk through which option actually fits before anything gets submitted to the IRS.
Frequently Asked Questions
What happens if the IRS accepts your offer in compromise?
You must meet every term in the accepted offer, including staying current on all future filings and payments for a set period. The IRS keeps your prior payments and does not release any related lien until you fully satisfy the terms.
What happens if the IRS rejects your offer in compromise?
You have 30 days to file an appeal with the IRS Independent Office of Appeals. A rejection often means the offer needs stronger documentation or was filed under the wrong grounds, not that you are permanently out of options.
How much should you offer to pay?
There is no fixed percentage. The IRS bases acceptance on your reasonable collection potential, a calculation of your income, expenses, and asset equity, not on what feels fair or what a company advertises as typical.
Is an offer in compromise the same as tax forgiveness?
Not exactly. It is one of several tools sometimes grouped under the IRS Fresh Start initiative. It can reduce what you owe if you qualify, but it is not a blanket forgiveness program, and eligibility depends entirely on your documented financial situation.
Can a church or nonprofit apply for an offer in compromise?
Yes. Churches and nonprofits can apply the same way individuals and businesses do, though the financial disclosure must account for restricted funds, grant agreements, and fund accounting rules that a generalist preparer may not know.
Do you need a CPA to file an offer in compromise?
It is not legally required, but the IRS itself notes that the program is not for everyone and recommends checking the qualifications of any tax professional you hire. A CPA who understands your specific financial structure, especially for a church, school, or nonprofit, can help make sure the numbers reflect your actual situation before they reach an IRS examiner.
Disclaimer: This article is for general educational purposes and does not constitute individualized tax, legal, or financial advice. Every offer in compromise is evaluated on its own facts. Speak with a licensed CPA or tax professional about your specific situation before applying.