Form 843 penalty abatement is the process of using IRS Form 843, Claim for Refund and Request for Abatement, to ask the IRS to remove or refund certain penalties you have already been charged, once you meet the qualifying rules. It is not a guarantee. The IRS reviews each request against specific criteria, and eligibility depends on your compliance history and the facts behind the penalty.
This guide covers who qualifies, how the form works, what changed in the most recent version, and where a recent court ruling fits in. Shaun Glenn, CPA, MSA, MST, reviewed it and has spent more than 15 years working with churches, nonprofits, schools, and closely held businesses on tax compliance and IRS matters.
What Is Form 843 and When Should You Use It
Form 843 is a multipurpose form. You use it to request a refund or an abatement of certain taxes, penalties, additions to tax, interest, and fees that the IRS has already assessed.
It is not the right form for every situation. The IRS is specific about this: you cannot use Form 843 to request an abatement of income, estate, or gift tax, and you cannot use it to request a refund of income tax or Additional Medicare Tax. For those, other forms and procedures apply.
For many of Simplicity Financial’s clients, Form 843 comes up after a specific event. A church misses a payroll tax deposit deadline during a leadership transition. A nonprofit files Form 990 late because a volunteer treasurer left mid-year. A closely held business gets hit with a failure-to-pay penalty after a cash flow gap. In each case, the tax itself is usually not in dispute. The penalty is what gets challenged.
Types of Penalties You Can Ask the IRS To Abate
Form 843 can be used to request abatement or refund of several penalty categories, including:
- Failure-to-file penalties, when a required return was filed late
- Failure-to-pay penalties, when tax owed was paid late
- Failure-to-deposit penalties, common with payroll tax deposits for multi-campus churches and organizations with several pay cycles
- Certain information return penalties, including some late-filing penalties tied to Form 990
- Interest that accrued because of an IRS error or unreasonable delay
Each penalty type has its own rules for what counts as a valid basis for relief, so the reason you give matters as much as the penalty itself.
Who Qualifies for Penalty Abatement
Two main paths to penalty abatement exist, and they work differently:
1. First-Time Abate: This is an administrative waiver, not a statute, and it covers failure-to-file, failure-to-pay, and failure-to-deposit penalties for a single tax period. To qualify, you generally need:
- No penalties assessed in the prior three tax years
- All currently required returns filed, or a valid extension on file
- Tax due either paid in full or under an approved payment arrangement
If your compliance history is clean and the current penalty is a one-time slip, First-Time Abate is often the more direct path, and it does not require you to explain why the penalty happened.
2. Reasonable cause: If you do not qualify for First-Time Abate, or you have already used it, the IRS will look at whether you had reasonable cause for the late filing or late payment. This requires specific, documented facts. Examples include a serious illness, a natural disaster that disrupted your operations, or reliance on incorrect written advice from the IRS itself. General explanations like being busy or unaware of the deadline typically do not meet the standard on their own.
Whether either path applies depends on your specific facts. A CPA can review your compliance history and the circumstances behind the penalty to help you understand which path fits and whether filing makes sense.
The December 2024 Form 843 Redesign: What Changed
The IRS revised Form 843 and its instructions, with the current version dated December 2024. If you are working from an older copy of the form, the line numbers and checkboxes will not match what the IRS expects on the current version.
Before filing, confirm you are using the current revision. Using an outdated form is one of the more common reasons a claim gets kicked back or delayed.
How to File Form 843 Step-by-Step
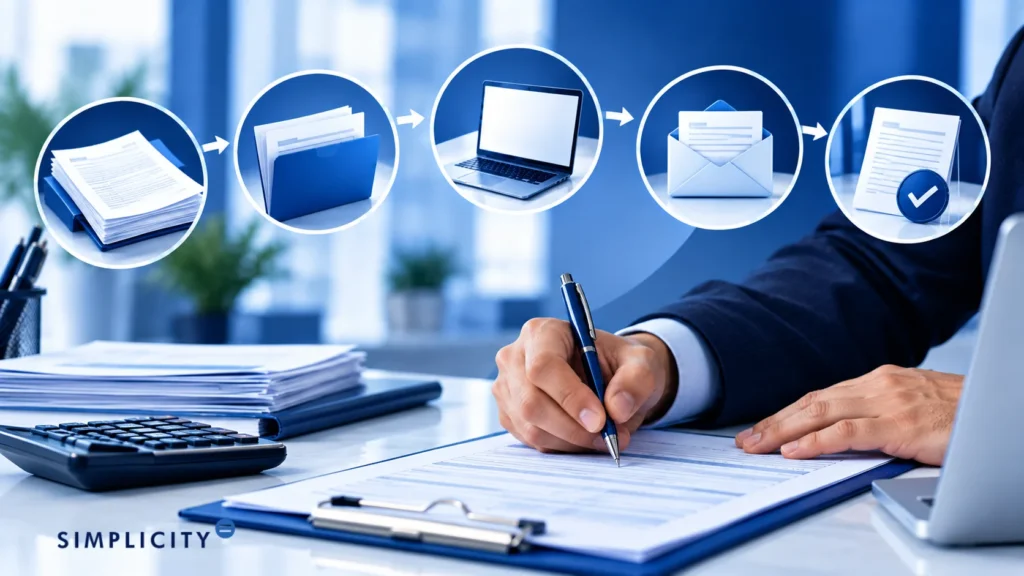
- Pull your IRS account transcripts for the tax years involved: These show exactly what penalties, interest, and payments the IRS has on record, and they should match what you put on the form. A CPA can request these transcripts on your behalf and flag anything that doesn’t match your own records before you file.
- Confirm which path applies: Check whether your prior three-year compliance history is clean enough for First-Time Abate, or whether you need to build a reasonable cause explanation. This is often where a CPA adds the most value, since reading a compliance history correctly takes some judgment, and misjudging it can mean filing under the wrong path.
- Complete the current version of Form 843: Identify the tax period, the specific penalty or fee, and the dollar amount you are claiming. A CPA can double-check that the entries match the December 2024 layout, since a mismatch between an old form and the current line numbers is one of the more common reasons a claim gets delayed.
- Attach a written statement: For First-Time Abate, a short reference to your clean compliance history is often enough. For reasonable cause, the statement must explain the specific facts, include dates, and reference any supporting documentation. A CPA can help make sure the statement is specific enough to meet the IRS standard, rather than a general explanation that gets denied on its own.
- Mail the form to the correct address: Send it to the IRS service center shown in the current instructions, or the address on the notice you received if the claim responds to a specific notice.
- Keep records and follow up: Keep a copy of everything you send, and follow up if you do not hear back within the timeframe the IRS gives for processing. If the IRS denies the claim or asks for more information, a CPA can help you decide whether to appeal, resubmit with additional documentation, or leave it as is.
The Kwong Ruling and COVID-Era Penalty Claims
In late 2025, the U.S. Court of Federal Claims ruled in Kwong v. United States that the COVID-19 disaster declaration automatically postponed federal tax filing and payment deadlines longer than the IRS had administratively recognized. In response, the IRS opened a window for taxpayers to file protective Form 843 claims tied to COVID-era penalties and interest, with a deadline of July 10, 2026, to preserve the claim while the government’s appeal was pending.
That filing window has now closed. As of this writing, the case remains under appeal, and the IRS has said it will only process these protective claims if the government’s appeal is unsuccessful. If you filed a protective claim before the deadline, the appropriate next step is to monitor the appeal rather than take further action right now. If you did not file by the deadline, this specific claim path is no longer available, though it does not affect your ability to request abatement under First-Time Abate or reasonable cause for penalties unrelated to the COVID-era postponement issue.
Common Mistakes That Sink a Form 843 Claim
- Filing without pulling account transcripts first, which leads to numbers that do not match IRS records
- Using an outdated version of the form instead of the December 2024 revision
- Requesting First-Time Abate after already receiving an abatement in the prior three years
- Submitting a reasonable cause statement with general explanations instead of specific, documented facts
- Missing the statute of limitations window
- Mailing the claim to the wrong service center
How Simplicity Financial Fits Into This
Penalty abatement decisions often come down to understanding the specific situation behind the penalty, not just filling out a form. Shaun Glenn, CPA, MSA, MST, has spent more than 15 years focused on nonprofit and church finance, including fund accounting, Form 990 preparation, multi-campus payroll, and clergy compensation rules like housing allowance and SECA. Those are the exact areas where failure-to-deposit and failure-to-file penalties tend to show up, and they’re a core part of the tax resolution services Simplicity Financial provides.
That specialization is the difference between a CPA-led review and a volume-based resolution mill. As a CPA in California who works with churches, nonprofits, schools, and closely held businesses, Shaun reviews each notice’s compliance history and the facts behind it before recommending a path forward.
Ready to Review Your Penalty Notice? Here’s the Next Step
If your church, nonprofit, school, or business received an IRS penalty notice and you’re not sure whether First-Time Abate or reasonable cause applies to your situation, Simplicity Financial can help review what happened and outline your options, whether that means scheduling a phone call or booking a Zoom call to walk through it together.
FAQs About Form 843 Penalty Abatement
What is IRS Form 843?
Form 843 is the form the IRS uses to process claims for a refund or abatement of certain taxes, penalties, interest, and fees already assessed.
Who needs to file IRS Form 843?
Anyone who was charged a penalty they believe qualifies for First-Time Abate or reasonable cause relief, and who is not requesting an income tax refund, can file Form 843 for that specific penalty.
How long does the IRS take to process a penalty abatement request?
Processing times vary, and the IRS does not guarantee a specific timeline. Keeping a complete, well-documented request reduces the chance of delays caused by missing information.
Can Form 843 be used to get an income tax refund?
No. The IRS specifically excludes income tax refunds, along with estate, gift, and Additional Medicare Tax abatements, from Form 843.
Disclaimer: This article is for general informational purposes only and does not constitute tax, legal, or accounting advice. Penalty abatement eligibility depends on your specific facts, compliance history, and the type of penalty involved. Nothing in this article creates a client relationship with Simplicity Financial. Consult a licensed CPA or qualified tax professional before filing a claim with the IRS.