If you can’t afford to pay your taxes in full, the IRS won’t send anyone to your door, and it won’t put you in jail. Instead, it will start charging penalties and interest on the unpaid balance, and if you ignore the bill long enough, it can eventually file a lien or levy your wages or bank account. The good news: the IRS offers several payment options, and choosing the right one early can keep a manageable bill from becoming a much bigger problem. In this blog, you’ll learn how each option works, how to tell which one actually fits your situation, and where a CPA’s review can save you from applying for the wrong one.
What Actually Happens If You Can’t Afford to Pay Your Taxes
Nothing dramatic happens the day after the filing deadline. What starts instead is a slow accumulation of interest and penalties, plus a series of notices that give you real chances to respond before anything escalates.
If you file on time but can’t pay, the IRS charges a failure-to-pay penalty of 0.5% of the unpaid balance for each month or partial month it goes unpaid, capped at 25% of what you owe. Interest accrues daily on top of that, currently around 7% annually, and it compounds until the balance is paid in full. The first notice you’ll typically see is a CP14, which lists what you owe and asks for payment within about three weeks. That letter starts a longer sequence, not a final demand.
The much steeper penalty applies if you don’t file at all: 5% of the unpaid balance per month, capped at 25%. That’s ten times the monthly cost of simply filing and dealing with the payment afterward. If you’re wondering what to do if you owe taxes but can’t pay in full, the most important thing to understand is this: file the return on time regardless, then handle the payment separately. Filing late because you can’t pay is one of the more common and most avoidable mistakes people make.
Your Options When You Owe More Than You Can Pay
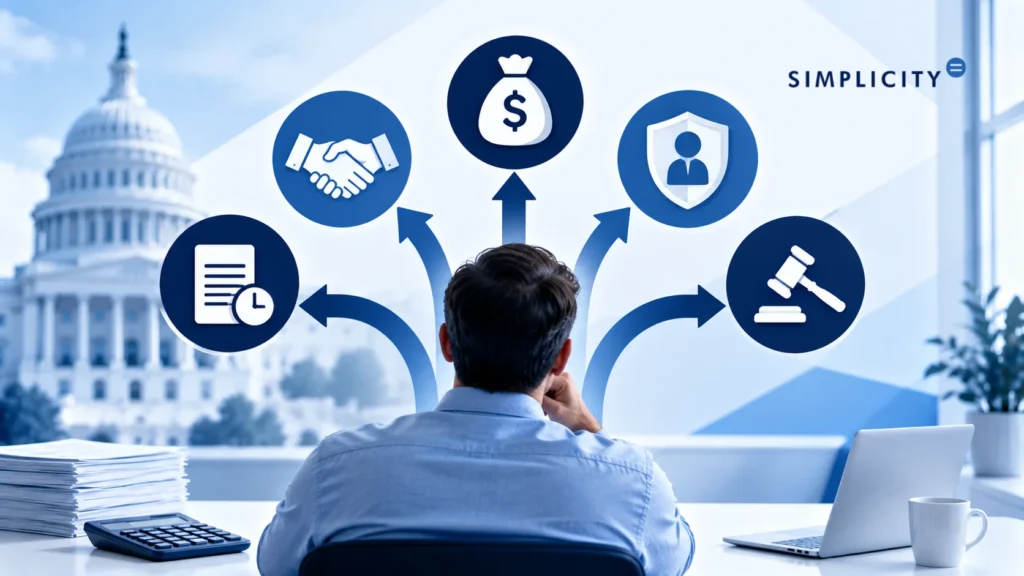
The IRS offers several paths for people who can’t pay in full, and most qualify for at least one without much difficulty. The options differ mainly in how much you owe, how long you need, and how firm your ability to pay actually is.
A Short-Term Payment Plan
If you can pay the full balance within 180 days, a short-term payment plan costs nothing to set up and is available for combined tax, penalties, and interest under $100,000. Interest and the standard failure-to-pay penalty keep accruing while the plan is active, but you avoid more aggressive collection action while you catch up. Setting up a payment plan with the IRS is usually the fastest option if you need a few extra months and expect to pay in full by then.
A Long-Term Installment Agreement
For balances of $50,000 or less that will take longer than 180 days to pay off, a long-term installment agreement lets you make monthly payments over as long as the IRS’s roughly ten-year collection window allows. Setup fees run from $22 (applied online with direct debit) to $69 (other payment methods), and low-income taxpayers can often have the fee waived or reimbursed. One meaningful benefit worth knowing: once an installment agreement is approved and the return is filed on time, the failure-to-pay penalty is cut in half, from 0.5% to 0.25% per month. This is one of a handful of options under the IRS’s broader Fresh Start program, and it helps to understand how the full set of Fresh Start options compares before applying for any single one.
An Offer in Compromise
An offer in compromise, authorized under 26 U.S. Code § 7122, allows certain taxpayers to resolve their tax debt for less than the full amount owed. The IRS bases acceptance on your Reasonable Collection Potential: essentially what it believes it could realistically collect from your income and assets over time, not on how much you’d prefer to pay. Approval isn’t automatic, and it depends entirely on your specific financial picture rather than the size of your tax bill.
Currently Not Collectible Status
If paying anything right now would prevent you from covering basic living expenses, food, housing, utilities, and similar essentials, you may qualify to have your account marked as currently not collectible. This temporarily pauses IRS collection activity, though penalties and interest continue to accrue in the background, and the IRS can review your finances later to see whether your ability to pay has changed. The process for applying for currently not collectible status involves documenting your income and allowable expenses in real detail, so it helps to know what the IRS is actually looking for before you submit anything.
Penalty Abatement
If this is your first time falling behind and you otherwise have a clean filing history, first-time penalty abatement can remove some of the penalties, though not the underlying tax itself or the interest tied to it. It’s most often used alongside a payment plan rather than as a stand-alone fix, and it rewards a track record of on-time filing more than it rewards hardship.
Which Option Actually Fits Your Situation
The right program almost always comes down to three questions: how much you owe, how long you realistically need to pay it off, and whether your finances can support payment at all right now. This table breaks down who tends to be a good fit for each option:
Program | Good Candidate If You… |
Short-Term Payment Plan (180 Days) |
|
Long-Term Installment Agreement |
|
Offer in Compromise |
|
Currently Not Collectible Status |
|
Penalty Abatement |
|
If more than one row looks like it could apply to you, that’s usually the clearest sign it’s worth having a CPA compare the math side by side before you apply for any of them.
What Happens If You Ignore the Notices
The IRS’s collection process moves in stages, not all at once. After the initial CP14 notice, an unpaid balance moves through a series of follow-up letters that escalate gradually in urgency and tone. If those go unanswered long enough, the IRS can eventually file a federal tax lien against your property or move toward levying a bank account or garnishing wages, but only after sending a Final Notice of Intent to Levy and giving you the right to request a hearing first.
None of this happens overnight, and each notice in that sequence is another opportunity to set up one of the options above before enforced collection starts. The costliest mistake in this process is letting the notices pile up unopened instead of responding to the first one, since each option above becomes harder to arrange the further collection has progressed.
Common Mistakes That Make This Harder Than It Needs to Be
Most of what turns a manageable tax bill into a bigger problem isn’t the balance itself; it’s an avoidable misstep along the way. These are the five that show up most often:
- Not filing at all: Skipping the return because you can’t pay the balance triggers the much steeper failure-to-file penalty for no real benefit.
- Defaulting to an offer in compromise: Most taxpayers who could actually afford a payment plan don’t qualify for an offer, and the application fee and paperwork go to waste if the numbers don’t support it.
- Agreeing to an unrealistic monthly amount: Committing to a payment plan without checking it against real cash flow usually ends in a default a few months in.
- Losing track of the collection window: The IRS generally has about ten years to collect, and that timeline affects how you evaluate these options.
- Paying upfront before anyone reviews your case: Handing a tax relief company a large fee before your numbers or filing history have actually been assessed rarely changes the outcome.
Most of these come down to the same root cause: moving forward with an option before confirming it fits, which a CPA review can usually catch before it costs you time or money.
A CPA’s Perspective
Shaun Glenn, CPA, MSA, MST, is a licensed CPA in California with more than 15 years of experience in tax and nonprofit finance, and founder of Simplicity Financial. Holding both a Master of Science in Accounting and a Master of Taxation, he’s seen the same pattern play out again and again with tax resolution clients: the math almost always points to one option being clearly better than the others, long before anyone fills out paperwork. The version of this that goes wrong is when someone applies for an offer in compromise because an advertisement promised debt reduction, spends months assembling the paperwork, and gets rejected because a payment plan was realistic all along. Running the numbers first, the way a licensed CPA is trained to, saves both time and money.
Where to Go From Here
Owing more than you can pay right now doesn’t automatically mean you’re in trouble. It means one of several IRS programs likely applies to your situation, and figuring out which one comes down to your actual numbers, not guesswork or whatever an advertisement happened to promise.
If you’d rather talk through your notice and balance out loud before deciding anything, schedule a phone call with Shaun and we’ll go over what you’re facing together. If you’d rather review your notices and return details with both of us at once, schedule a Zoom call instead. Either way works, and neither one commits you to anything beyond that first conversation.
Frequently Asked Questions
What happens if you can’t afford to pay your taxes?
The IRS still expects the return to be filed on time, and a failure-to-pay penalty plus daily interest begin accruing on the unpaid balance. You’ll typically have several options available, including a short-term or long-term payment plan, an offer in compromise, or currently not collectible status, depending on your financial situation.
Will the IRS keep my tax refund if I owe back taxes?
Yes. If you have an outstanding federal balance, the IRS can apply any future refund to that balance instead of sending it to you, a process known as a refund offset. This applies whether or not you’re on a payment plan, so plan for a smaller refund, or none at all, until the balance is resolved.
Does a payment plan or currently not collectible status affect my credit score?
The IRS doesn’t report payment plans or currently not collectible status to the credit bureaus directly. A federal tax lien, if one is filed, can still show up in public records and affect financing in other ways, which is one more reason to address a balance before it reaches that stage.
Do I need to handle my California state taxes separately if I can’t pay?
Yes. The IRS and the California Franchise Tax Board run separate collection processes with their own notices, payment plans, and deadlines. Resolving a federal balance doesn’t automatically resolve a state one, and vice versa, so both need attention if you owe both.
Can I apply for these programs myself, or do I need a CPA?
Most individuals can apply for a short-term plan or a long-term installment agreement directly through the IRS without help. Offer in compromise and currently not collectible status involve more financial documentation and judgment calls, which is where a CPA’s review tends to matter more.
What if I also owe payroll taxes for my business?
Payroll tax debt carries its own risks, including potential personal liability for the owner, and is handled somewhat differently than individual income tax debt. If that’s part of your situation, it’s worth treating it as a distinct conversation alongside anything covered here.
Disclaimer: This article is provided for general informational purposes and does not constitute tax, legal, or accounting advice. Every taxpayer’s situation is different, and eligibility for any IRS program depends on individual facts and circumstances. Consult a licensed CPA before applying for a payment plan, offer in compromise, or currently not collectible status.